Table of Contents
Appraisal comps are recent sales of similar homes near the property being appraised, and the appraiser adjusts them for their differences to reach a value. Fannie Mae wants comps that closed within the last 12 months, sets no fixed distance limit, and requires at least three closed sales in every report.
Because the comps drive the final number, picking the wrong ones can push a value too high or too low. This guide covers the comparable guidelines appraisers follow and the characteristics they look for in comps.
How far back and how far away do appraisers look for comps?
Appraisers usually start with sales from the last 3 to 6 months in the subject's own neighborhood and widen the search only when they run short. The Fannie Mae Selling Guide says comps that closed within the last 12 months should be used, and older sales are allowed when the report explains why.
There is no mileage rule. The one-mile radius people hear about is a habit, not a requirement.
| Question | Short answer |
|---|---|
| How far back can comps go? | Fannie Mae: closed within the last 12 months, older allowed with an explanation. Most appraisers look at the last 3 to 6 months first. |
| How far away can comps be? | No fixed limit. Comps should come from the subject's market area or a competing one, and the report states each comp's straight-line distance. |
| How many comps are needed? | At least three closed sales. Listings and pending sales can be added as support but don't count toward the three. |
What are comparables?
In most residential appraisal reports, the value comes from the sales comparison approach. The appraiser takes sales of comparable properties from the neighborhood and adjusts each one for features that are better or worse than the subject property.
Sale comparables, or "comps," are the sales and listings the appraiser decides are most similar to your home. They are usually recent, nearby, and alike in many ways.
Some neighborhoods make this easy. In a planned development with a handful of floor plans, the appraiser can often find sales of the exact same model.
A house out in the country is different. The nearest comps may be miles away and not very similar at all.
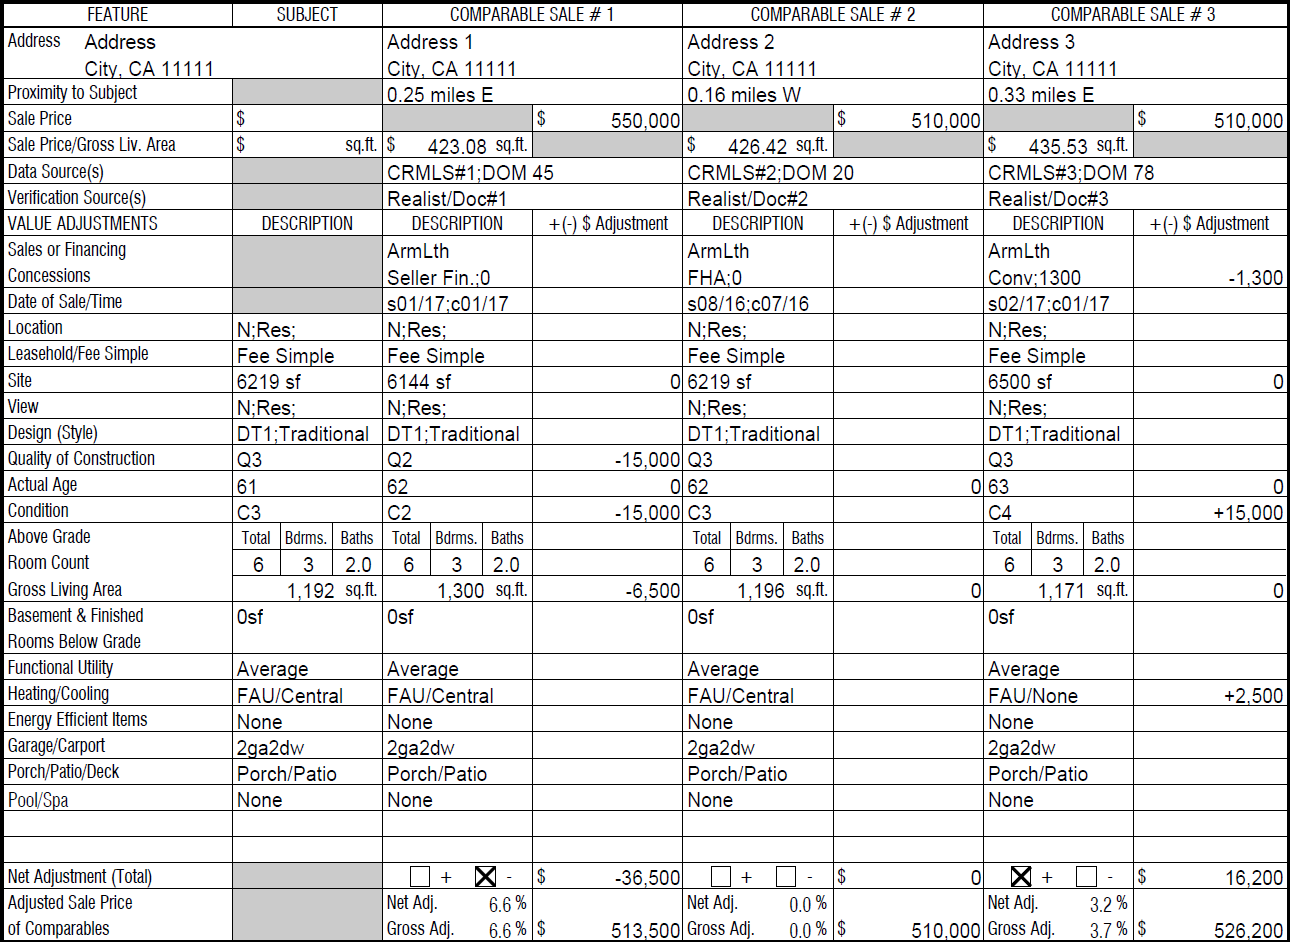
An example of comps in an appraisal report is shown below. The three comparables in this grid share a lot with the subject property. The first has a similar lot, view, style, room count, heating and cooling, and parking, and the other two match on many features as well.
For a walk through the rest of the report, see this guide on how to read an appraisal.
How do appraisers choose comps?
Appraisers choose comps by pulling every recent sale near the subject property from the local MLS, then filtering that list down to the sales that are closest, most recent, and most physically similar to the subject. From that shortlist, they select the three or more sales that a buyer of your home would most likely have considered instead. RealVals follows these comp guidelines in every market value appraisal and date of death appraisal in San Francisco and Marin County.
- Step 1: search the MLS (and sometimes public records) for closed sales in the subject's neighborhood, often starting close by and within the last 3 to 6 months.
- Step 2: narrow by similarity: living area, condition and quality ratings, lot, view, style, and property type.
- Step 3: pick the final set so the subject's features are bracketed, with at least one comp superior and one inferior, then adjust each comp for its differences.
Appraisal comparable guidelines
Most appraisers follow the same general guidelines when choosing comps, but none of them are set by law.
Lenders and Fannie Mae have published guidelines over the years. Sometimes following a rule of thumb to the letter would produce a less credible report, and in that case the appraiser is expected to use better data and explain it.
The general rule is simple: find the most similar properties, as close as possible, that sold as recently as possible. Broken down characteristic by characteristic, it looks like this.
Location
Location is one of the most important things an appraiser weighs when choosing comps.
The comps should come from the subject's own neighborhood or from similar, competing neighborhoods nearby. Fannie Mae allows comps from a competing neighborhood as long as the appraiser says so and addresses the differences. It also says the appraiser must not stretch the neighborhood boundaries just to fit the comps that were picked.
Some neighborhoods have plenty of sales close by, and some have almost none. Either way, the comps should come from areas that compete with the subject for the same buyers.
A sale from a dissimilar neighborhood can throw the value off badly, especially if the appraiser doesn't know the area. When there aren't enough comps nearby, the appraiser widens the search area or goes further back in time.
Site size (lot size)
There is no set percentage an appraiser has to stay within for lot size, but there are good rules to follow.
Besides size, the appraiser should look at lot utility and topography. Size matters most, but a pie-shaped lot can be worth less than a rectangular one, and a sloping lot less than a flat one.
In Austin Fernald's market, a large sloping lot often sells for about the same as a flat lot half its size. Usable yard space matters a lot where families are the main buyers.
It is up to the appraiser to decide whether these lot traits add to or take away from value, but all of them should be considered.
View
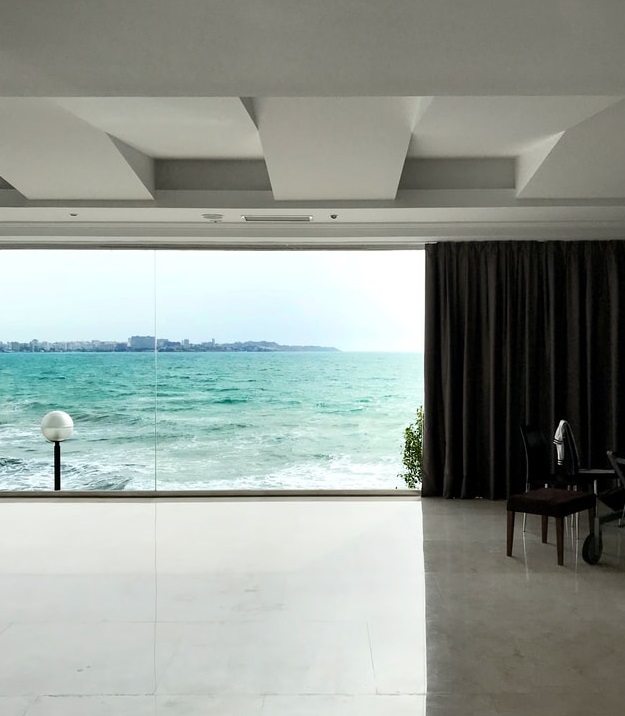
View is another feature an appraiser should look at. There are no specific guidelines for it, but it should always be taken into account.
Most homes have a residential neighborhood, woods, or pasture view, and there is usually no value difference between those.
Value comes in when the view can be enjoyed from inside the house. Homes with water, city, or golf course views usually sell for more than homes without them, so the best comps have similar views to the subject.
Condition and quality
Condition and quality are two of the biggest drivers of a home's value. Adjustments for them can be large, so appraisers try to avoid needing them.
Condition
Condition is the home's current state of maintenance, wear, and updating.
A standard 1004 single-family appraisal report rates condition on six levels, C1 to C6. C1 is a brand new house, and C6 is a house with damage so serious it affects safety or livability.
Quality
Quality refers to the materials and workmanship used to build or remodel the house. Like condition, it has six levels, Q1 to Q6.
Q1 means high-end finishes, custom construction, and professional workmanship. Q6 means the lowest quality materials, sometimes without systems (electrical, plumbing, etc.) you would expect in a typical house.
For both ratings, the appraiser looks for comps that match the subject or sit within one level in either direction, since these can be some of the largest adjustments in the report.
Size (GLA)
Size, or gross living area (GLA), is the finished above-grade living space of the home being appraised.
A common rule of thumb is to keep comps within about 25% of the subject's size, larger or smaller. Fannie Mae doesn't set a percentage limit, but the logic holds up.
By that rule, a 1,300 square foot comp is a stretch for a 1,000 square foot subject, and so is a 700 square foot house.
Once the size gap gets large, the homes start to appeal to different buyers and the adjustments get harder to support. A 4,000 square foot house and a 5,000+ square foot house, for example, probably don't draw the same buyers and wouldn't make good comps for each other.
Best practices for comparable sales
Location, lot, view, condition, quality, and size are where the appraiser should be strictest. A few more best practices round out comp selection.
Distance
Appraisers try to stay as close to the subject as the market allows. In a dense city, a few blocks may be enough. In a rural area, comps several miles away can be normal.
Fannie Mae doesn't set a maximum distance. The appraiser must report each comp's distance in miles, measured in a straight line, with a direction (for example, "1.75 miles NW"). For rural properties, Fannie Mae accepts distant comps if they produce credible results and the report explains them.
Crossing into another city or school district usually means a different market, so appraisers avoid it when they can and explain it when they can't.
FHA appraisal comps: generally accepted distance
Neither FHA nor Fannie Mae publishes a hard distance limit for comps. The one-mile radius is a rule of thumb, not a regulation. Both expect comps from the subject's neighborhood or a competing one, and both expect the appraiser to explain any comp from outside it.
- FHA (HUD Handbook 4000.1) requires at least three sales that closed within 12 months of the effective date, plus more data when needed to support the value.
- FHA used to require two sales closed within 90 days and two listings in rising or falling markets. HUD removed that requirement in Mortgagee Letter 2025-18 (June 2025, now part of HUD Handbook 4000.1), though a lender can still ask for listings.
- Fannie Mae's guideline is that comps should have closed within the last 12 months, with older sales acceptable when explained.
Sale date
Most appraisers look first at sales from the last six months. If there are not enough good ones, they go back further, up to 12 months and sometimes beyond with an explanation.
An older sale in the home's own neighborhood is usually better than a newer sale in a non-competing neighborhood further away.
Retrospective work is different. In California, a property tax appeal appraisal uses sales around the January 1 lien date, not the most recent ones.
Closed date
A property that closed after the effective date of the appraisal should not be used as a sold comparable. It can still be included as a listing.
Bracketing
An appraiser should try to "bracket" each feature of the subject property. Bracketing is a term appraisers use when the chosen comps include some that are better and some that are worse than the subject.
At least one comp should be superior on a given feature and at least one inferior. If Comparable 1 has a larger lot than the subject and Comparable 3 has a smaller one, lot size is bracketed.
Bracketing isn't required, but it is good practice.
Adverse influences
An adverse influence is anything nearby that hurts a property's value. Examples include large power lines in the backyard, a commercial building across the street, or a high school behind the house.
If the appraiser decides it has a negative effect, it should be mentioned in the report and adjusted for. Ideally, at least one comp has the same or a similar adverse influence.
Property types
Property type should always match. An appraiser should never use a condominium as a comp for a single-family home, or a single-family home as a comp for a condo.
Do comps need the same property rights as the subject?
Yes. Appraisers should try to use comparable properties that include the same property rights as the subject property. A fee simple home should be compared to other fee simple sales, and a leasehold property to other leasehold sales.
- Property rights affect value directly: a home on leased land typically sells for less than an identical home where the buyer owns the land.
- If the appraiser must use a comp with different property rights, an adjustment and explanation are required.
- Matching rights, location, and physical traits all keep adjustments small.
Can an appraiser use outside comps in a condo appraisal?
Yes, but sales inside the subject's own project usually come first. Fannie Mae prefers comps from the same market area, including the same project, when possible. An appraiser who goes outside the complex should explain why in the report.
- Same-project comps are strongest because they share the HOA, amenities, construction quality, and location, which removes most adjustments.
- If the project has no recent sales, the appraiser moves to competing condo projects nearby that attract the same buyers.
- For new or recently converted projects, Fannie Mae requires at least one closed comp from inside the project and at least one from outside it, with limited exceptions when the project has no closed sales yet.
- A single-family home is still never an acceptable comp for a condo. "Outside" means outside the project, not outside the property type.
How to do an appraisal when there aren't any comps
When there are no ideal comps, the appraiser still has to complete the assignment. They widen the search until they find the best data available, then explain the choices in the report. The value is still credible as long as the reasoning and adjustments are supported.
- First moves: widen the search to competing neighborhoods, go back 12 months or more, and look at active and pending listings alongside closed sales.
- For truly unique properties, the appraiser can lean on the cost approach (land value plus construction cost minus depreciation) or the income approach to support the value.
- Older or distant comps can be adjusted for market changes over time and for location. A well-adjusted older sale from the same neighborhood usually beats a recent sale from a non-competing area.
This is why an appraiser sometimes uses more distant comparables. It isn't a shortcut. It means the closer sales weren't similar enough.
Conclusion
No law spells out which comps an appraiser has to use, but the guidelines above are widely followed.
It comes down to finding the most similar, most recent, and closest sales to your house. Those are the comps that best show what a buyer would pay for it.
Frequently asked questions about appraisal comparables
Yes, if you know of good ones. Most appraisers welcome any information the owner provides. The appraiser has probably already found them, but Austin Fernald has had homeowners point him to off-market sales and to sales he hadn't found in his own research.
Usually 3 to 6 months to start, and up to 12 months if needed. Fannie Mae says comps that closed within the last 12 months should be used. Older sales are allowed when the appraiser explains why, which happens in slow or rural markets. The more recent the sale, the better, because markets keep changing.
There is no fixed limit. Fannie Mae and FHA don't set a maximum distance; the comps just need to come from the subject's neighborhood or a competing one. A one-mile radius is a common starting point in suburbs, but city comps are often much closer and rural comps can be several miles away. Distant comps need an explanation in the report.
Mostly from the local MLS (Multiple Listing Service), which records nearly all listed sales in an area. Appraisers occasionally use sales from public records that were never listed on the MLS.
The most similar, most recent, and closest sales to your property. The best comps are homes a buyer of your home would also have considered buying.
At least three closed sales. Fannie Mae requires a minimum of three closed comparables in the sales comparison approach, and FHA also requires three closed within 12 months. Most appraisers include more, often four to six, mixing closed sales with active or pending listings. Listings can support the value but don't count toward the three closed sales. There is no maximum.
Yes. A cash sale is a valid comparable as long as it was an arm's-length sale at market value. How the buyer paid doesn't change what the property sold for. The appraiser should confirm the sale wasn't distressed (foreclosure, short sale, sale between relatives). Financed comps with large seller concessions may be adjusted down to reflect the effective price. In investor-heavy markets, leaving out cash sales would ignore a large part of the market.
Go through the lender, not the appraiser: ask for a reconsideration of value (ROV) and submit better comparables with the request. Since 2024, Fannie Mae, Freddie Mac, and FHA all require lenders to have a formal ROV process that borrowers can start. Stick to facts: closer, more recent, or more similar sales, or factual errors in the report (wrong square footage, missed upgrades). A few strong sales work better than a list of ten weak ones. "The value is lower than I wanted" is not grounds for an ROV.
In a typical home appraisal, the comps are the value. The sales comparison approach is the main method for nearly all home appraisals, and the final number comes from the adjusted sale prices of the chosen comps. Swapping one comp for another can move the value by thousands of dollars. The cost and income approaches, when used at all, usually serve as support.
