Table of Contents
- What is an appraisal report?
- Home appraisal report sections
- Home appraisal report example
- Cover page or appraiser cover letter
- Page one: subject
- Page one: contract
- Page one: neighborhood
- Page one: site
- Page one: improvements
- Page 2: sales comparison approach
- Page 2: reconciliation and value
- Page 3: additional comments
- Page 3: cost approach
- Page 3: income approach
- Page 3: PUD information
- Pages 4-6: boilerplate
- Sketches, maps, photos
- Additional information
- What to look for in an appraisal report
- Conclusion
- Frequently asked questions
An appraisal report is the written document in which a licensed or certified appraiser gives an opinion of a property’s market value as of a specific date, along with the data and reasoning behind that number. To read one, start with the final value in the reconciliation section, then check the property facts and the comparable sales that support it.
Most reports run 20 pages or more, and a lot of that is boilerplate. Whether the appraisal is for a purchase, a refinance or a divorce, the guide below walks through the report section by section so you know which parts matter.
The examples use this Uniform Residential Appraisal Report sample, the form most often used for conventional purchase and refinance loans.
What is an appraisal report?
An appraisal report is the appraiser’s written opinion of a property’s market value, supported by the facts used to reach it. In plain terms, the meaning of an appraisal report is “here is what this home was worth on this date, and here is why.” It includes property details, neighborhood information, comparable sales, photos, maps, a sketch and the appraiser’s reasoning.
- For most home loans, the report is prepared on the Uniform Residential Appraisal Report (URAR, Fannie Mae Form 1004 / Freddie Mac Form 70).
- The lender, not the borrower, is the appraiser’s client, even though the borrower usually pays for the appraisal. For a first mortgage on a home, the lender must give the borrower a copy.
- Since November 2, 2026, Fannie Mae and Freddie Mac require new appraisals in a redesigned, dynamic URAR (UAD 3.6) that replaces the numbered forms (1004, 1073, 2055 and others) with one report that adapts to the property type. Lenders that requested a temporary exception may submit the older format until May 2027, and the older layout this guide follows will still show up on reports for a while.
- For date of death appraisals and other private work, appraisers typically use a general-purpose form such as the GP Residential form.
Home appraisal report sections
The main part of a Form 1004 home appraisal report is six pages long.
- Page one: subject, contract, neighborhood, site and improvements.
- Page two: the sales comparison grid, with the reconciliation and final value at the bottom. Extra comparables go on added pages, which don’t count toward the six.
- Page three: additional comments, the cost and income approaches, and a section for planned unit developments (PUDs).
- Pages four through six: boilerplate required in every 1004 report.
Around those six pages you’ll usually find a cover page or letter, photos, maps, a sketch and other supporting documents.
Home appraisal report example
So what does an appraisal report look like? The screenshots in each section below come from a real, completed Form 1004 report, so they match what you’ll see in your own home appraisal. A typical report is laid out like this:
- Pages 1-3: the filled-in form, covering the subject property, neighborhood, site and improvements, the sales comparison grid, and the final reconciled value.
- Pages 4-6: standard boilerplate, including certifications, limiting conditions and the appraiser’s license information.
- Addenda: photos of the subject and each comparable, a building sketch with dimensions, location maps, and any supplemental market analysis.
Cover page or appraiser cover letter
The cover page is usually the first page of the appraisal. It lists the home address, a photo and the client, and sometimes the appraised value and a table of contents.
Some appraisers use a cover letter instead, explaining the assignment, the subject property and the client.
Page one: subject
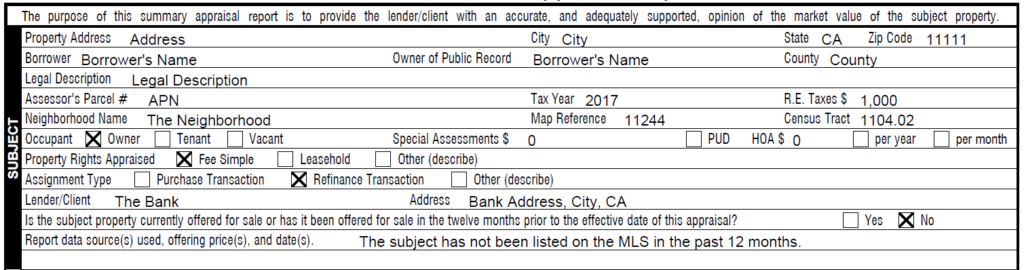
The subject section identifies the property, the assignment and the client. It starts with the address, then the borrower and the owner of public record.
Next come the legal description, assessor’s parcel number, tax year and annual taxes. After that: neighborhood name, occupant, PUD and HOA information, property rights appraised and assignment type (purchase, refinance or other).
The section ends with the lender or client and whether the home was listed for sale in the 12 months before the appraisal.
Page one: contract
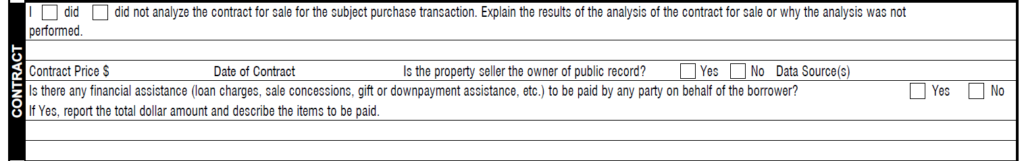
The contract section is only filled in when the appraisal is for a purchase. It covers the sale itself: contract price, contract date and any seller concessions.
Page one: neighborhood
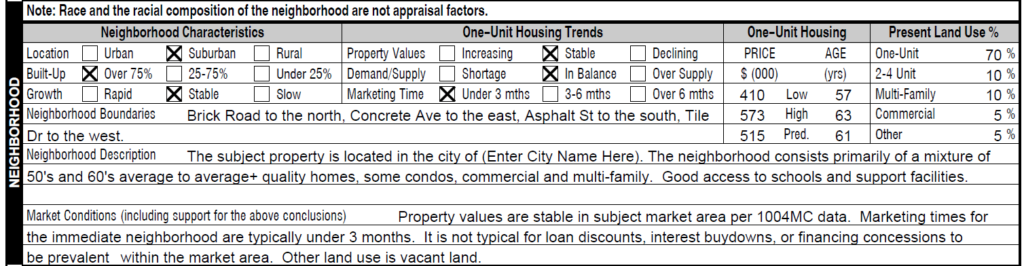
The neighborhood section opens with location (urban, suburban or rural), how built-up the area is and its growth rate.
“One-Unit Housing Trends” reflects property values, supply and marketing time for homes that compete with yours. “One-Unit Housing” covers the whole neighborhood, with the low, high and predominant prices and ages.
Present land use is usually an estimate, split into one-unit, 2-4 unit, multi-family, commercial and other. The boundaries and description fields should define the neighborhood on all four sides, and the market conditions comment explains what the appraiser found in the competing sales.
What is the predominant value on an appraisal?
The predominant value is the most common sale price for one-unit homes in the subject’s neighborhood, reported alongside the low and high ends of the price range in the neighborhood section. It’s a mode, not an average.
- If the appraised value sits far above the predominant value, underwriters may look for signs of over-improvement, meaning a home built beyond what the neighborhood supports.
- A value near or below the predominant value generally signals the home is typical for its market, which supports marketability.
- The same box reports predominant age, which works the same way for the age of homes in the neighborhood.
Page one: site
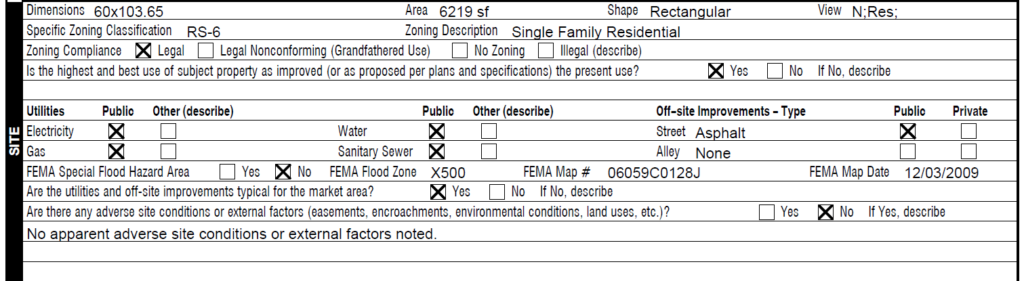
The site section describes the land. It starts with lot dimensions, size, shape and view. For an irregular lot, the dimensions field often just says “Refer to Plat Map.”
Next are the zoning and whether the home complies with it. Highest and best use comes after that. It matters more to the appraiser than to you, since it simply asks whether the current use is the most valuable legal use of the property.
Then come utilities, off-site improvements and flood zone information. The last checkboxes flag adverse site conditions or external factors, such as a busy road or an adjacent commercial property.
Page one: improvements
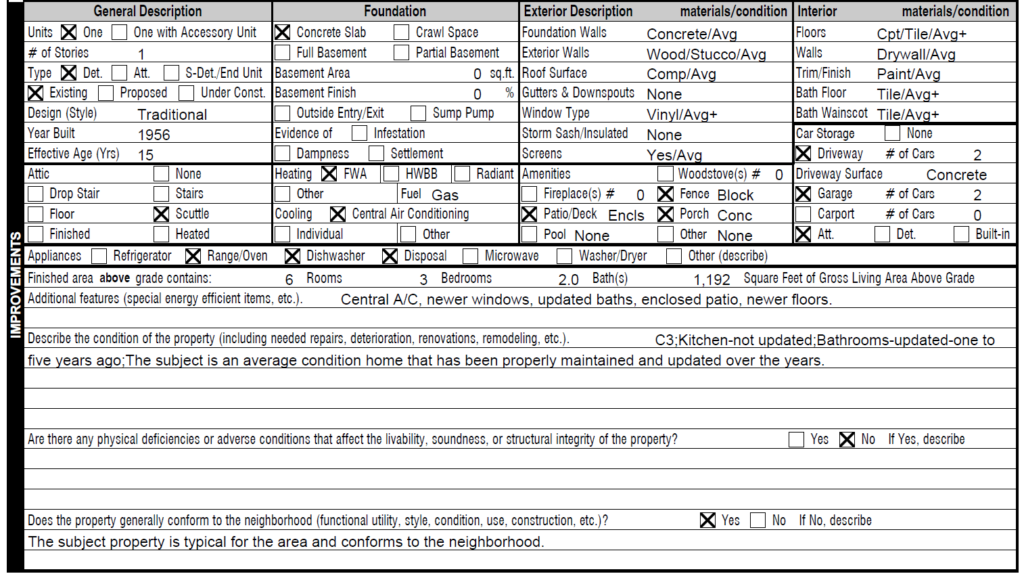
The improvements section describes the house itself. It starts with the number of units and stories, type, design, actual age and effective age.
Effective age reflects the condition and updating of the house rather than the year it was built. A 50-year-old house that has been fully updated could have an effective age of 15.
After that come the foundation and basement, exterior and interior materials and their condition, attic, heating and cooling, amenities (fireplaces, patios and decks, fences, pool, spa) and car storage.
The rest is written commentary. Additional features often mention things like solar. Then the appraiser describes the home’s condition, notes any physical problems that affect livability or soundness, and says whether the home conforms to the neighborhood.
Page 2: sales comparison approach
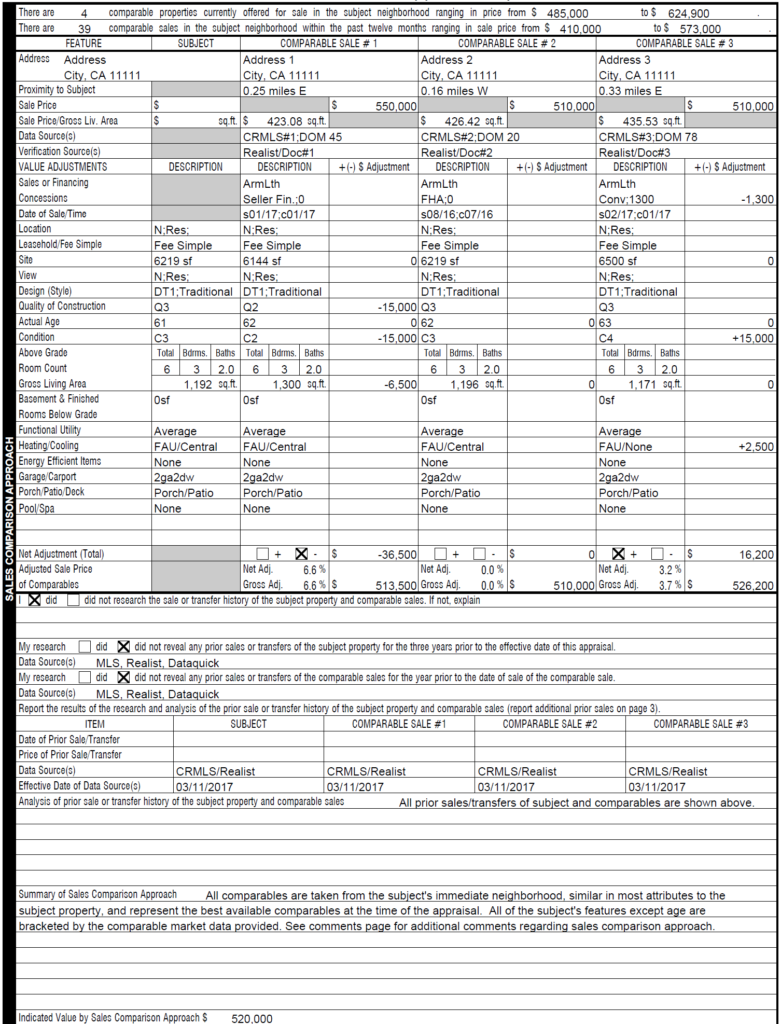
Page two drives the value. The top lines summarize how many comparable listings and sales are in the neighborhood, then the comparable grid takes up most of the page.
Comparables are recent sales the appraiser picks because they are close by (ideally in the same neighborhood) and similar to your home. In a tract neighborhood they can be nearly identical. In a more varied area they will differ more.
The appraiser adjusts each comparable’s sale price for its differences from your home, such as size, condition, bathrooms or view. The adjusted prices should land in a reasonably tight range. A wide spread is something underwriters question.
On a 1004, this approach usually gets the most weight in the final value. Below the grid are prior sales of the subject and the comparables, a summary of the approach and its indicated value.
Page 2: reconciliation and value
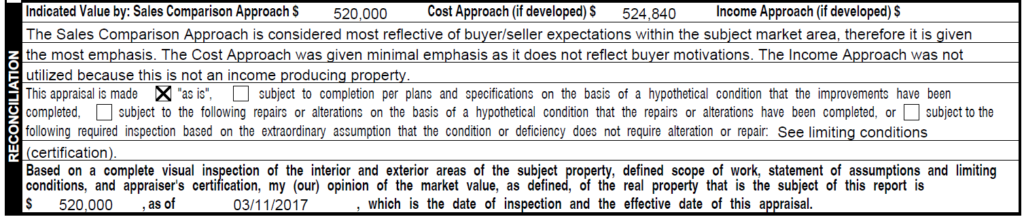
If you read only one section of the appraisal report, read this one. It is where the approaches to value are reconciled into the final appraised value.
Across the top are the indicated values from the sales comparison, cost and income approaches. The sales comparison approach always has a value. The cost and income approaches are filled in only when the appraiser decides they are needed for a credible result.
These are the three main approaches to value.
Next is a checkbox for “as is” or “subject to.” Most appraisals are as is. If the home is under construction or needs repairs, one of the “subject to” boxes is checked.
The final line is the appraised value, the value conclusion for your property.
What does “subject to” mean on an appraisal?
An appraisal made “subject to” means the value depends on something happening first: completion of construction per plans and specifications, completion of specific repairs, or a required inspection. Until that condition is met, the value is hypothetical rather than final.
The lender will typically require a follow-up completion report (Form 1004D) confirming the work was done before the loan can close.
An “as is” appraisal values the property in its current condition with no strings attached. FHA and VA appraisals are more likely to come back “subject to” repairs, because those programs enforce minimum property standards.
Page 3: additional comments
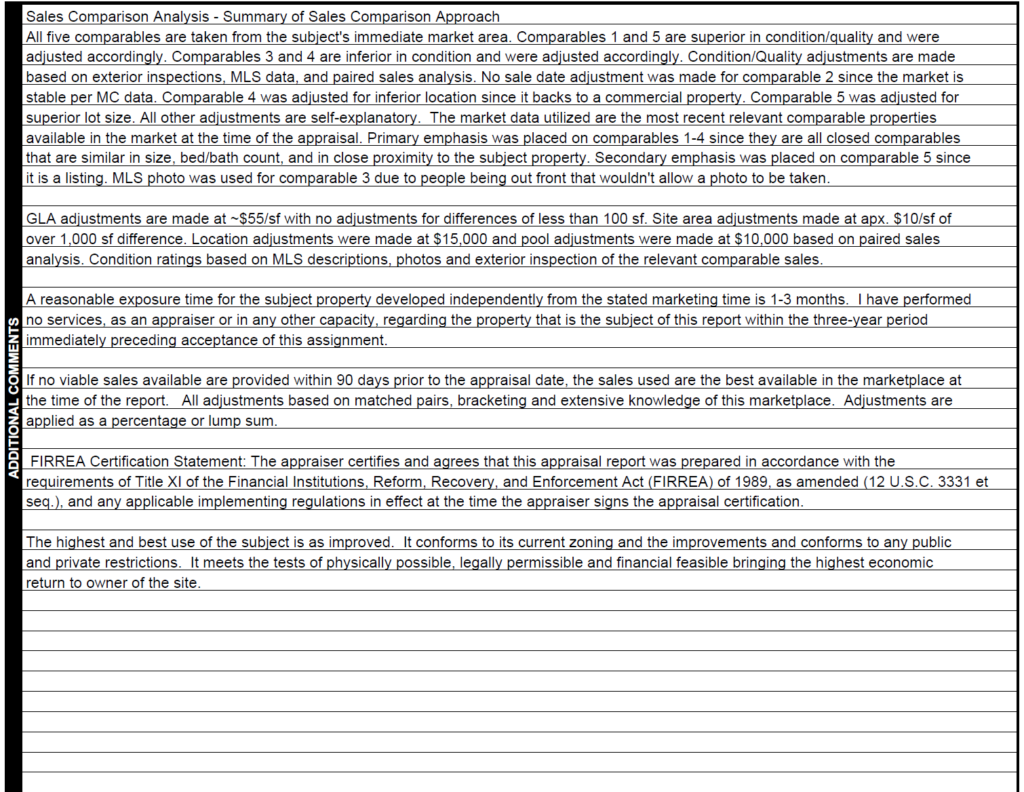
Page three is the last page of property-specific information in the main form. The comments box may hold all of the appraiser’s commentary, or it may be blank with the comments moved to an addendum at the end.
Page 3: cost approach
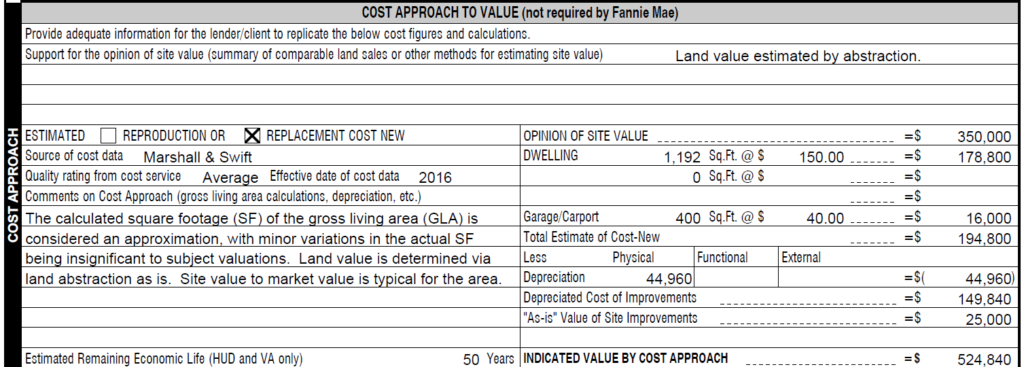
The cost approach may or may not be filled in. Some lenders require it even when it adds little.
It works like this: site value, plus the cost new of the improvements, minus depreciation, plus the “as is” value of site improvements such as landscaping and driveways.
The cost approach works well for new construction with land sales nearby. It is much less reliable for older homes, or where there are no land sales to support the site value.
Page 3: income approach

This section is usually blank unless the home is a rental. The income approach value is the estimated monthly market rent times a gross rent multiplier.
Page 3: PUD information
This section is filled in when the home is in a planned unit development. It covers the unit type, project name and unit counts, then the common facilities and whether they are complete and controlled by the HOA.
Pages 4-6: boilerplate
Pages four through six of the form are standard text: the scope of work, definitions, limiting conditions and the appraiser’s certifications and signature. They rarely tell you anything about your specific home.
Sketches, maps, photos
After the form pages come the property-specific sketches, maps and photos. If page three had no long write-up, the appraiser’s comments addendum usually lands here too.
The building sketch shows the exterior dimensions with the rooms labeled. Appraisal software calculates the square footage from the exterior measurements the appraiser took at the inspection.
Order varies by appraiser, but a typical set also includes the plat or parcel map (the recorded map of the lot), an aerial map, a location map of the subject and comparables, photos of your home, and photos of each comparable.
Additional information
Past the sketches, maps and photos you may find more boilerplate, supporting documents, charts or a market conditions addendum.
A market conditions addendum explains price trends based on the data the appraiser found. Some lenders require one, but most reports today do not include it.
What to look for in an appraisal report
Focus your review on three things: whether the facts about your property are correct, whether the comparable sales are reasonable, and what the final value is conditioned on. Factual errors are the most common problem in appraisal reports, and the most fixable.
- Verify the basics: address, gross living area, bedroom and bathroom count, lot size, condition rating, and any upgrades or renovations you told the appraiser about.
- Check the comparables: they should be recent sales (ideally within the last 6-12 months), close to the subject, and genuinely similar in size, condition and style.
- Note whether the value is “as is” or “subject to” repairs or completion. A “subject to” value isn’t final until the condition is met and verified.
- If you find a material error, you can request a reconsideration of value (ROV) through your lender. Lenders can also order a desk review appraisal, where a second appraiser checks the report without visiting the property. On a mortgage appraisal, borrowers go through the lender rather than contacting the appraiser directly.
For what the appraiser checks during the visit itself, see what a home appraiser looks for.
Conclusion
Most of an appraisal report is boilerplate, maps, photos and supporting documents. The parts that decide the value are on the first three pages: the facts about your home, the comparable grid and the reconciliation.
If an appraisal is coming up, this home appraisal checklist helps you prepare.
Frequently asked questions
The appraised value appears in two places. It is usually on the cover page with the property and client information, and it is always in the reconciliation section at the bottom of page two, below the sales comparison grid.
Most appraisal reports go to the lender within about a week of the inspection, and the whole process from order to finished report often takes one to two weeks. Turnaround can stretch in busy markets or areas with few appraisers. The on-site inspection itself is short, usually 30 minutes to a couple of hours. Most of the appraiser’s time goes into researching comparables and writing the report.
Yes. For a first mortgage on a home, federal law (the ECOA Valuations Rule) requires the lender to give you a copy of each appraisal promptly upon completion, or three business days before closing, whichever is earlier. You can waive the timing and get it at closing instead. If the loan doesn’t close, the copy is generally due within 30 days.
Your appraisal results are the final opinion of value, found on the cover page and in the reconciliation section, plus any conditions attached to it, such as required repairs. What happens next depends on how that value compares to your contract price or loan amount. If the value is at or above the contract price, the loan proceeds normally, based on the lower of price or value. If it is below, the buyer can renegotiate, bring extra cash to cover the gap, request a reconsideration of value through the lender, or walk away if an appraisal contingency allows it. Results marked “subject to” repairs must be resolved and re-verified before closing.
