Table of Contents
- What is a desktop appraisal?
- What is a desktop valuation?
- Desktop appraisal vs full appraisal
- Desktop appraisal fee
- Hybrid appraisal vs desktop appraisal
- Desk review appraisal vs desktop appraisal
- Commercial desktop appraisal
- Desktop appraisal companies
- Which one is right for you?
- Conclusion
- Where desktop appraisals stand in 2026
- Desktop appraisal FAQ
A desktop appraisal is an appraisal completed without anyone inspecting the property. The appraiser works from MLS records, public records, maps, and other data to reach an opinion of value, usually faster and for a lower fee than a full appraisal.
Homeowners, brokers, lenders, developers, and investors all use them. A desktop appraisal is a new opinion of value, which is different from a desk review appraisal that checks a report another appraiser already wrote.
What is a desktop appraisal?
A desktop appraisal is an appraisal that is completed without the appraiser ever leaving their desk. There's no interior inspection, no exterior inspection, and no measuring. The entire appraisal is completed from the desk.
The appraiser relies on data from third-party sources. MLS, public records, and aerial and street-level maps are the main ones, but there are many others.
Sites like ZoningPoint.com help with zoning information, and many cities and counties have online permit portals that show whether work has been done on a property.
A desktop appraisal is prepared by a licensed or certified appraiser. It is not the same as a CMA (comparative market analysis), an AVM (automated valuation model), or a BPO (broker price opinion).
It is a real appraisal report, and it can be used for many purposes.
What is a desktop valuation?
A desktop valuation is a property value estimate completed entirely from the valuer's desk using online records, sales data, and mapping tools, with no site visit. In the US the two terms overlap. A desktop appraisal is a formal appraisal signed by a licensed appraiser, while "valuation" is the broader term that can also cover automated valuation models, evaluations and broker opinions.
- In the UK and Australia, desktop valuation is the standard industry term, which is why the phrase shows up so often in international articles.
- A desktop valuation report contains the same core analysis as any appraisal: subject data, comparable sales, adjustments, and a final value conclusion.
- If a lender needs the result, ask whether they require a desktop appraisal by a licensed appraiser or will accept an automated or broker-prepared valuation.
Desktop assessment, desktop survey, and desktop analysis: are they the same thing?
In real estate, desktop assessment, desktop survey, and desktop analysis all describe the same idea as a desktop appraisal: evaluating a property remotely from existing data instead of visiting it. The terms differ mainly by country and profession, not by method.
- "Desktop survey" is common UK usage, where surveyors (their equivalent of appraisers) perform remote property assessments.
- "Desktop assessment" and "desktop analysis" are looser terms that can also cover zoning reviews, environmental screenings, or feasibility checks done from public records.
- Outside real estate, "desktop assessment" usually means a review of computers and IT setups, which has nothing to do with property value.
- Only a version signed by a licensed or certified appraiser counts as an appraisal. The rest are informal estimates or research products.
Desktop appraisal vs full appraisal
Put simply, a desktop appraisal is a full appraisal without the inspection. Nobody measures the house, takes photos, or looks at its condition in person.
The analysis in the report is the same, but the property data comes from third-party sources instead of the appraiser's own visit. For many properties, that costs accuracy.
Desktop appraisals are more likely to miss the mark on properties with:
- Little data online
- Wrong data online
- Complex or hidden features that don't show up on maps or in third-party records
- Few similar comparables
They tend to work well for houses that are:
- In tract neighborhoods
- In average condition with no recent upgrades
- Well documented online
- Surrounded by plenty of comparable sales
- Recently sold
In short, desktop appraisals work for "cookie-cutter" homes in planned developments, not for unique properties.
Here is an example of a property a desktop appraisal would not work well for:
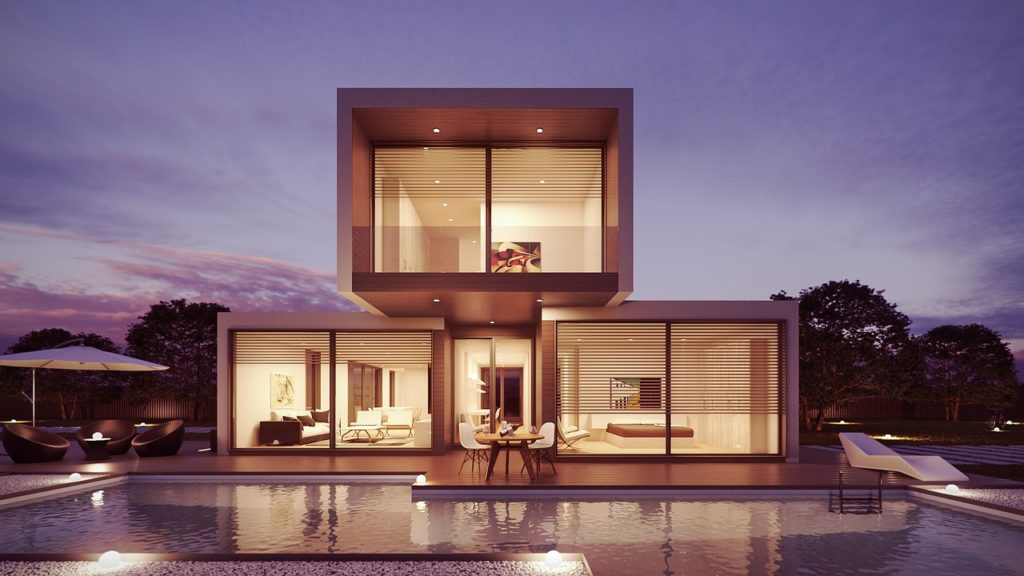
This house is one of a kind. An appraiser would struggle to find good comparables and would need to see it in person to judge its condition, quality, and quirks.
Here is an example of homes a desktop appraisal would work well for:
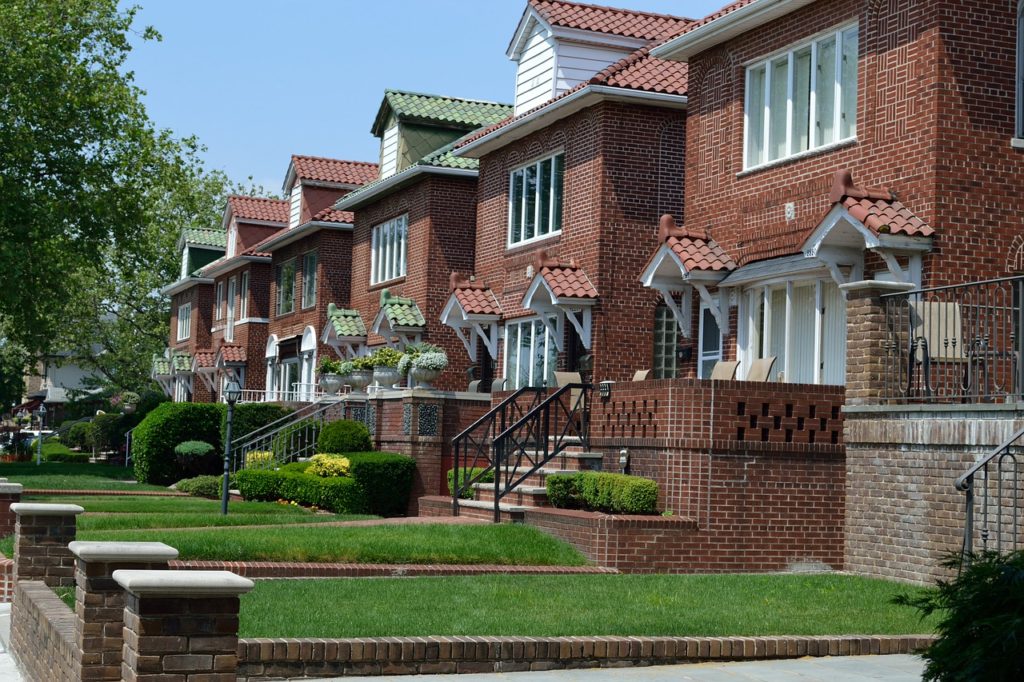
These homes look alike in style, condition, quality, and appeal. They were likely built around the same time with similar materials, and they are probably close in size and lot size.
That makes them much better candidates for a desktop appraisal.
A full appraisal involves the same research and comparable selection. The difference is the in-person inspection.
The inspection lets the appraiser gather first-hand data, get an accurate read on condition and quality, and spot anything unusual about the property.
Without it, the appraiser can miss major deferred maintenance or expensive upgrades that third-party sources don't mention. That is why, for a date of death appraisal or a divorce appraisal, where the IRS or the other side may question the value, RealVals inspects the home in person.
Online data may not show that a property has a pool or a 1,000 square foot addition in the back. An inspection will.
Accuracy
Accuracy is the main concern when comparing a desktop appraisal to a full one.
A desktop appraisal can come close to a full appraisal if enough good data is available. If the data is thin or wrong, the value is mostly guesswork.
That is why traditional lenders kept away from desktop appraisals for years, and why Fannie Mae and Freddie Mac still limit them to lower-risk loans.
Data keeps getting better. Public records are online, and sites like Zillow show listing details and photos, though appraisers still rely on the MLS and verify what they find.
Aerial imagery can help an appraiser check a home's footprint, and street-level imagery shows the property from the street. Some map tools also offer 3D views of a property.
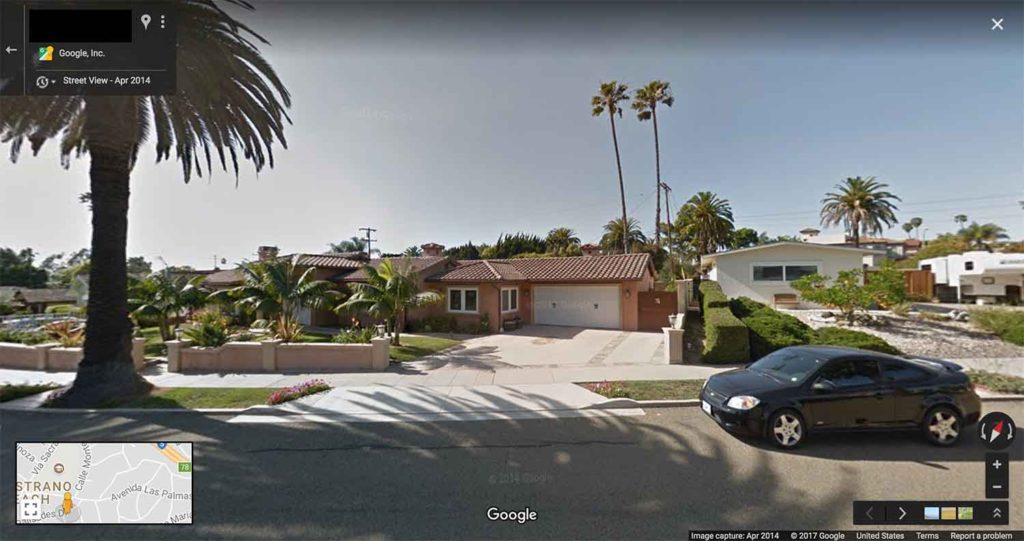
Street View images can be years old, though. The one above was captured in 2014. Better data narrows the gap, but it doesn't close it.
Benefits
Desktop appraisals are best for getting a quick value from a licensed appraiser.
They usually cost less than a full appraisal, and the turnaround is faster since there's no inspection to schedule.
For that reason, investors and private lenders often use them. Anyone who needs a quick value on a straightforward property should consider one.
Drawbacks
Accuracy is the main drawback. The appraiser never sees the property, so the report has to rest on assumptions about it.
For some intended users that's fine. Others, like the IRS or the other side in a divorce, are more likely to question a value the appraiser never saw in person.
Desktop appraisal fee
Desktop appraisals are usually one of the lower-cost appraisal options. Fees are set by each appraiser and vary by market and property, so there is no standard price.
As a reference point, a full appraisal from RealVals starts at $500 for a single-family home or condo and $700 for a 2-4 unit property. Ask any appraiser for a written quote before ordering.
Is there such a thing as a free desktop appraisal?
No. A desktop appraisal signed by a licensed appraiser always carries a fee, because a person researches the property and stands behind the value. The free property estimates online are automated valuation models, and courts, the IRS and lenders do not accept them in place of an appraisal.
- The free options are an automated valuation model, such as a Zillow estimate, or a broker price opinion prepared by an agent rather than an appraiser.
- On a lender-ordered desktop, the borrower pays the fee and it appears on the Loan Estimate appraisal fee line.
- Expect a desktop quote below a full appraisal, which starts at $500 for a single-family home or condo at RealVals.
Hybrid appraisal vs desktop appraisal
A hybrid appraisal is essentially a desktop appraisal with an inspection: a trained property data collector visits the home to gather photos, measurements, and condition data, and the appraiser develops the value from their desk using that data. A pure desktop appraisal has no inspection by anyone.
- The hybrid fixes the desktop's biggest weakness (unknown interior condition) while keeping much of the speed.
- Fannie Mae and Freddie Mac both offer hybrid appraisals on certain loans when their underwriting systems allow it.
- Cost and turnaround usually fall between a desktop and a full appraisal, since someone still has to visit the property.
Desk review appraisal vs desktop appraisal
A desk review is not a desktop appraisal. A desktop appraisal values a property; a desk review evaluates another appraiser's existing report, checking the data, comps, adjustments, and conclusions for accuracy without leaving the desk.
- Lenders order desk reviews for quality control, loan buybacks, fraud investigations, and second opinions on questionable reports.
- Appraisal reviews follow their own USPAP standard (Standard 3).
- A desk review can agree with the original value, flag problems, or, in some assignments, develop the reviewer's own opinion of value.
Commercial desktop appraisal
Desktop appraisals exist on the commercial side too, usually as restricted appraisal reports or evaluations used for portfolio monitoring, loan renewals, and smaller transactions. The analysis leans on rent rolls, operating statements, and market data rather than a site walk-through.
- Federal banking rules allow lenders to use an evaluation instead of a full appraisal for commercial real estate transactions of $500,000 or less, which is where desktop products fit most often.
- Larger or more complex commercial properties still get full narrative appraisals, because income analysis and physical condition drive their value.
Desktop appraisal companies
Desktop appraisals reach lenders through the same channels as traditional appraisals. Appraisal management companies (AMCs) assign them to independent licensed appraisers on their panels, and many AMCs and valuation firms run desktop and hybrid programs for lenders.
- For lenders, the AMC handles ordering, appraiser assignment, and quality control, the same as with full appraisals.
- Investors and homeowners can skip the AMC and hire a local appraiser directly.
- Appraisers write desktops in the same software as any other report. A desktop is a scope-of-work decision, not a separate technology.
How do you choose a desktop valuation provider?
Check three things before ordering: that the person signing holds a current state appraiser license, that the quote names the scope of work (desktop, hybrid or full), and that the product is an appraisal rather than an automated valuation model or a broker price opinion.
- California licenses are searchable through the Bureau of Real Estate Appraisers, and every state's licensees also appear on the Appraisal Subcommittee National Registry.
- Ask who signs the report. An appraisal management company takes the order and assigns it to an independent appraiser on its panel.
- For an estate, divorce or tax appeal, confirm the intended user will accept a report with no inspection before paying for one.
Which one is right for you?
It depends on the intended use of the appraisal and who will rely on it.
For a refinance, a desktop appraisal won't work for a Fannie Mae or Freddie Mac loan; both limit desktops to purchases. For a pre-listing appraisal, an estate, or a divorce, a full appraisal with an inspection is usually the safer choice.
If you are an investor who needs a quick value and the data is there, a desktop appraisal may be enough.
Conclusion
Desktop appraisals are a good way to learn what a property is worth when a quick value is all you need.
They are cheaper and faster than a full appraisal and can come close in accuracy when the data is good. They won't replace a full appraisal for unique homes or high-stakes uses, but they are now a standard option.
Where desktop appraisals stand in 2026
What started as a COVID-era workaround is now a permanent mortgage option. Fannie Mae and Freddie Mac have both accepted desktop appraisals on eligible purchase loans since March 2022, and both also offer hybrid appraisals.
Under the Fannie Mae Selling Guide, a loan qualifies for a desktop appraisal only when it meets all of these:
- One-unit property (including one with an ADU or a unit in a PUD)
- Principal residence
- Purchase transaction, including new construction
- Loan-to-value ratio of 90% or less
- Desktop Underwriter (DU) Approve/Eligible recommendation, with DU offering the desktop option
Refinances, condos and co-ops, 2-4 unit properties, manufactured homes, second homes, investment properties, and manually underwritten loans are not eligible. Freddie Mac's rules are similar: a 1-unit primary residence purchase with a maximum 90% LTV.
For appraisers, desktops are a scope-of-work option that trades inspection data for speed. The appraiser is responsible for a credible result either way.
Lenders now choose from a range of options matched to loan risk: value acceptance (no appraisal), value acceptance plus property data (data collection only), hybrid, desktop, exterior-only, and full appraisal.
The forms are changing too. On November 2, 2026, the redesigned URAR (UAD 3.6) became mandatory for new Fannie Mae and Freddie Mac appraisal submissions, though lenders granted a temporary exception may submit the older format until May 2027. Instead of separate forms like the 1004 Desktop, one dynamic report adapts to the scope of inspection performed.
Desktop appraisal FAQ
A desktop appraisal is an appraisal without an inspection. It is completed by a licensed or certified real estate appraiser using MLS, public records, and other third-party data.
Usually, yes. With no inspection, the appraiser spends less time on the assignment, and the fee is typically lower than for a full appraisal. Fees vary by appraiser and market.
Often a day or two, depending on the appraiser's schedule. With no inspection, there's no appointment to set up and no site visit, which removes most of the waiting.
A desktop appraisal has no inspection. A full appraisal includes an interior and exterior inspection, or at least an exterior-only inspection. For a desktop, the appraiser relies on third-party data, which can lead to errors in the report. Desktop appraisals are usually cheaper and faster.
Not as a rule. A desktop can miss in either direction because the appraiser can't see what the data doesn't show. Missed upgrades push the value low, and missed deferred maintenance pushes it high. If your home is renovated beyond what public records show, a desktop may undervalue it, so offer interior photos and a list of improvements up front. When the data is too thin, a careful appraiser will decline the desktop assignment rather than guess.
For typical homes in markets with good data, a desktop appraisal by a licensed appraiser can land close to what a full appraisal would conclude. Accuracy falls off on unique properties, thin markets, and homes whose interior differs from what records suggest. The appraiser is limited by the MLS, public records, and imagery. That's why lenders keep desktops for lower-risk loans and order full appraisals when the stakes or the uncertainty are higher.
Yes. Homeowners can order a desktop appraisal directly from a licensed appraiser for non-lending uses such as pricing a home, estate planning, or general curiosity. No lender is needed. Ask the appraiser specifically for a desktop appraisal and get a fee quote. A homeowner-ordered appraisal can't be used for a mortgage, because lenders order their own appraisals. Interior photos, a floor plan, or a list of upgrades make a desktop much more accurate, since the interior is its biggest blind spot.
